
The Chicago Mercantile Exchange (often referred to as the “Merc”) stands as a colossus in the global financial landscape. Its story is not merely one of financial innovation but a narrative deeply intertwined with the agricultural heartland of the United States and the evolving needs of commerce. Understanding its creation requires a journey back to the late 19th century, a period of rapid industrialization and expanding markets, where the seeds of this influential institution were sown amidst the burgeoning economy of Chicago.
The Agricultural Roots of a Financial Giant
The genesis of the Chicago Mercantile Exchange can be traced directly to the needs of America’s agricultural producers and consumers. As the nation expanded westward, Chicago emerged as a critical hub for the distribution of agricultural commodities. Grain, livestock, and dairy products flowed into the city from across the vast Midwest, destined for processing and consumption both domestically and internationally.

The Need for Price Discovery and Risk Management
Before the formal establishment of organized exchanges, trading in agricultural goods was often fragmented and opaque. Farmers selling their harvests and merchants buying them faced significant price volatility. A bumper crop could lead to a sudden glut and plummeting prices, devastating producers. Conversely, a poor harvest could send prices soaring, impacting consumers and downstream industries. This inherent uncertainty made long-term planning and investment difficult.
The burgeoning trade necessitated mechanisms for more reliable price discovery. Buyers and sellers needed a central marketplace where supply and demand could interact openly, leading to a more transparent and fair valuation of goods. Furthermore, the inherent risk associated with fluctuating commodity prices spurred a desire for tools that could help manage this uncertainty. This unmet need created fertile ground for the development of a formal trading institution.
Early Forerunners and Informal Markets
The direct precursor to the Chicago Mercantile Exchange was not a singular entity but rather a series of evolving trading practices. Early markets in Chicago were often informal gatherings where traders would haggle over prices. These were rudimentary but served a crucial function: connecting buyers and sellers and establishing a baseline for commodity values.
As the volume of trade grew, so did the complexity of these interactions. The need for standardized contracts, reliable information, and a structured trading environment became increasingly apparent. This led to the formation of various commodity associations and boards, each focusing on specific agricultural products. These organizations provided a framework for trading, albeit with varying degrees of formality and regulation. The Chicago Board of Trade (CBOT), established in 1848, was a significant early player, primarily dealing with grains. While the CBOT laid crucial groundwork, the specific needs of other commodity sectors, particularly those not directly tied to grain, would eventually necessitate a distinct exchange.
The Birth of the Chicago Butter and Egg Board
The direct lineage of the Chicago Mercantile Exchange can be precisely dated to 1898 with the establishment of the Chicago Butter and Egg Board. This entity was born out of a distinct need within the dairy and poultry industries. While the Chicago Board of Trade focused on grains, the producers and merchants of butter and eggs found themselves facing similar challenges of price volatility and market access.
Uniting Diverse Interests
The formation of the Chicago Butter and Egg Board brought together a diverse group of stakeholders: dairy farmers, egg producers, commission merchants, wholesalers, and retailers. Each had a vested interest in a more stable and predictable market. The board provided a centralized location for these participants to meet, negotiate, and execute trades.
Standardized Contracts and Quality Control
A key innovation of the Chicago Butter and Egg Board was the development of standardized contracts for butter and eggs. Prior to this, transactions were often based on individual agreements, leading to disputes over quality, quantity, and delivery terms. Standardized contracts introduced a level of predictability and trust into the trading process.
Furthermore, the board implemented quality grading systems. This was particularly important for perishable goods like butter and eggs, where variations in quality could significantly impact value. By establishing clear quality benchmarks, the board facilitated more equitable trading and encouraged producers to maintain higher standards. This focus on standardization and quality was a critical step towards the eventual transformation into a broader futures exchange.
Evolution into the Chicago Mercantile Exchange and Futures Trading
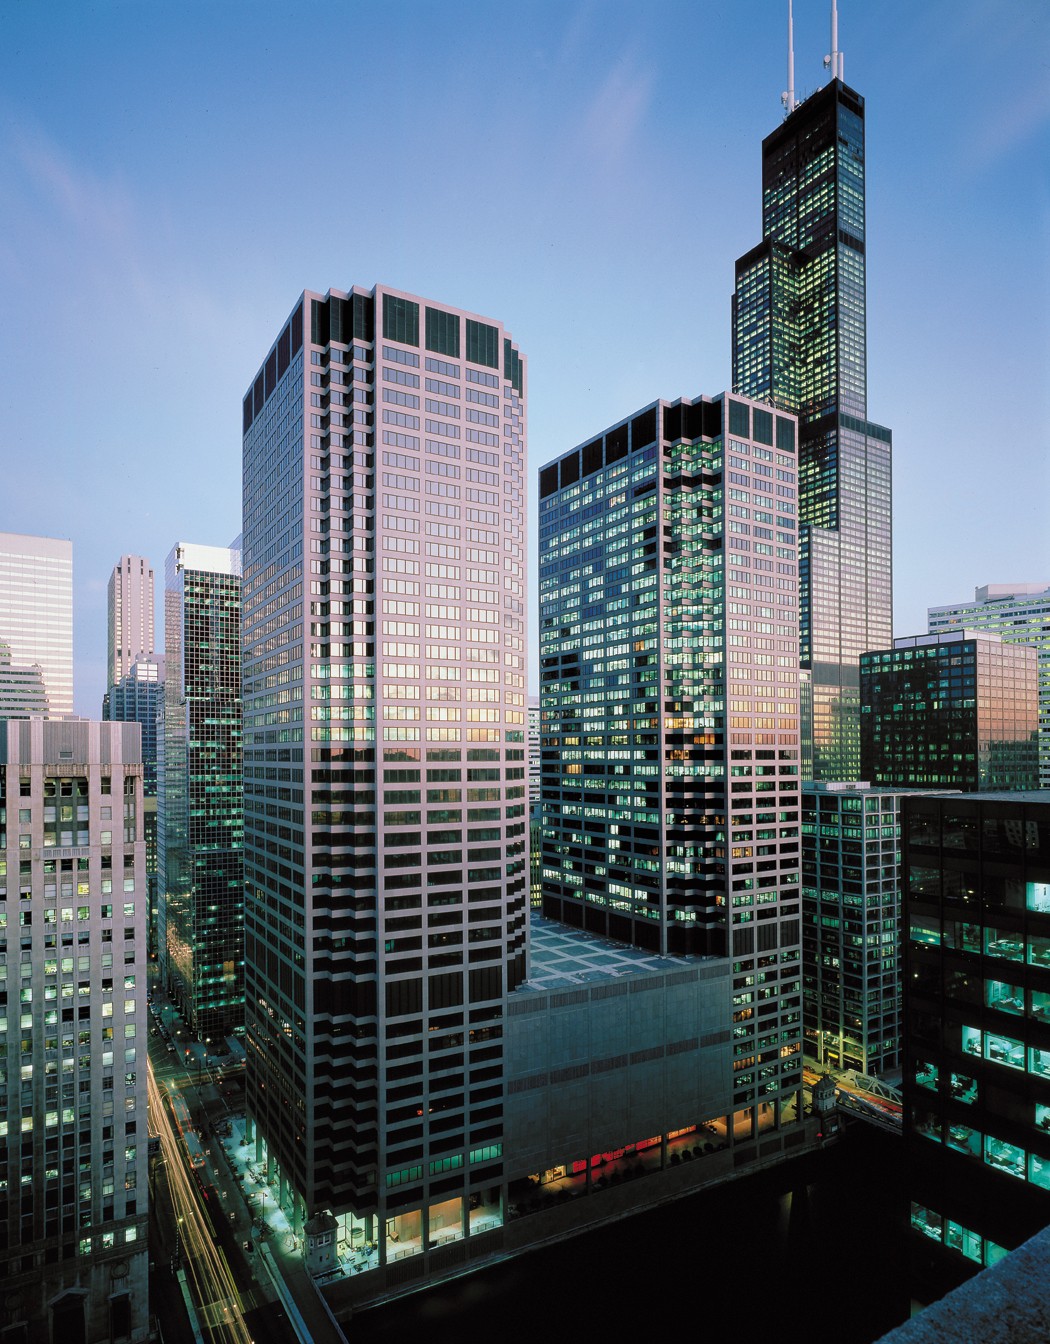
The Chicago Butter and Egg Board, while successful in its niche, was destined for a broader role. As the 20th century progressed, the financial landscape evolved, and the concept of futures contracts gained wider acceptance. The board recognized the potential to expand its scope beyond simply spot trading and to offer instruments that could hedge against future price fluctuations.
The Transition to a Futures Exchange
In 1919, the Chicago Butter and Egg Board underwent a significant transformation, renaming itself the Chicago Mercantile Exchange. This rebranding signaled an ambition to diversify its offerings and to cater to a wider range of commodities. The primary driver behind this evolution was the development and popularization of futures contracts.
Futures contracts are agreements to buy or sell a specific commodity at a predetermined price on a future date. These instruments were revolutionary because they allowed producers, processors, and speculators to lock in prices, thereby mitigating the risks associated with market volatility. For a farmer, selling a futures contract on their upcoming crop provided certainty about the revenue they would receive. For a manufacturer, buying a futures contract ensured they could secure raw materials at a known cost.
Key Innovations and Expansion
The Chicago Mercantile Exchange quickly became a leader in the development and trading of futures contracts for a variety of agricultural products, including cattle, hogs, lumber, and eventually, financial instruments. The exchange pioneered new contract specifications and trading methodologies to meet the evolving needs of its participants.
The concept of open outcry trading, where traders physically congregated on the trading floor to execute orders verbally, became synonymous with the Merc for decades. This dynamic and often chaotic environment facilitated rapid price discovery and allowed for the efficient execution of trades. While the advent of electronic trading has since transformed the landscape, open outcry was a cornerstone of the Merc’s early success.
The Chicago Mercantile Exchange also played a pivotal role in the development of commodity options, which provide the buyer with the right, but not the obligation, to buy or sell a futures contract at a specific price. This further enhanced the risk management capabilities available to market participants.
The Modern Era: Diversification and Global Reach
From its humble beginnings as a marketplace for butter and eggs, the Chicago Mercantile Exchange has grown into one of the world’s largest and most sophisticated derivatives marketplaces. Its creation was a response to fundamental economic needs, and its evolution reflects a continuous adaptation to market dynamics and technological advancements.
Expansion Beyond Agriculture
While its roots are firmly planted in agriculture, the Chicago Mercantile Exchange has dramatically diversified its product offerings over the decades. Recognizing the increasing interconnectedness of global markets, the Merc began listing futures and options on a wide array of financial instruments. This includes interest rates, stock indexes, currencies, and even alternative investments.
The listing of Eurodollar futures in the 1980s was a landmark moment, transforming the Merc into a major player in the global interest rate derivatives market. The exchange has consistently adapted, launching contracts on popular stock indexes like the S&P 500 and introducing new products to meet the demands of institutional investors and traders worldwide.
Technological Advancements and Electronic Trading
The late 20th and early 21st centuries brought about a revolution in trading technology. The Chicago Mercantile Exchange was at the forefront of embracing these changes. While open outcry served the market well for generations, the efficiency and accessibility offered by electronic trading platforms became undeniable.
The exchange invested heavily in developing and acquiring sophisticated electronic trading systems. The introduction of platforms like Globex, the CME’s proprietary electronic trading system, allowed for 24-hour trading and significantly increased liquidity and order execution speed. This transition from a physical trading floor to a predominantly electronic marketplace has been a defining characteristic of the modern Chicago Mercantile Exchange, enabling it to serve a global clientele with unparalleled efficiency.

Mergers and Acquisitions
The drive for scale and diversification has also led to significant consolidation in the financial exchange landscape. The Chicago Mercantile Exchange has been a key participant in this trend. A pivotal moment was its merger with the Chicago Board of Trade in 2007, creating the CME Group. This strategic union brought together two of the world’s oldest and most respected derivatives exchanges, enhancing their collective product offerings and market reach. Subsequently, the CME Group has continued to grow through further acquisitions, solidifying its position as a dominant force in the global derivatives market.
The creation of the Chicago Mercantile Exchange is a testament to the power of market-driven innovation. It began as a solution to the specific challenges faced by agricultural producers and evolved into a global powerhouse, shaping financial markets and facilitating risk management for industries and investors across the spectrum. Its journey from a humble butter and egg board to the sophisticated derivatives marketplace it is today is a compelling chapter in the history of commerce and finance.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.