
Navigating the intricacies of inheritance, particularly concerning taxation, can be a complex endeavor for Floridians. While the prospect of receiving an inheritance is often a welcome one, understanding the tax implications is crucial for effective financial planning and avoiding unexpected liabilities. This article aims to demystify the tax landscape surrounding inheritances in Florida, focusing on state-level implications and clarifying the absence of a state estate or inheritance tax.
Understanding Florida’s Tax Landscape for Inheritances
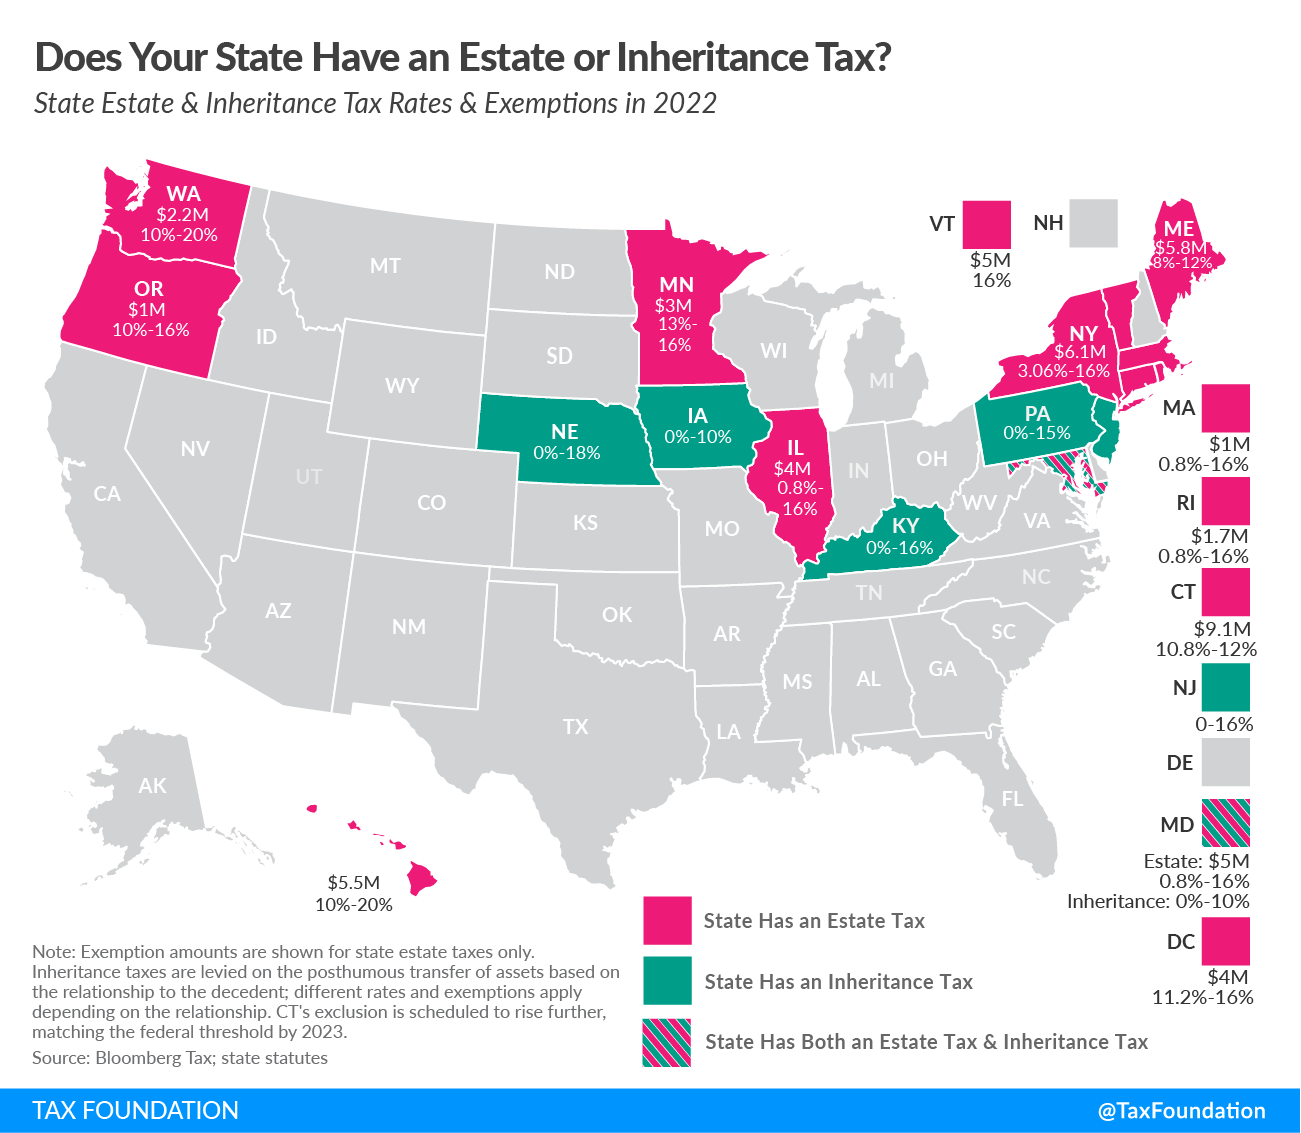
Florida stands out as one of a select few states that do not impose an estate tax or an inheritance tax on assets passed down to beneficiaries. This is a significant advantage for inheritors, as it means the full value of the inherited assets, in many cases, will not be subject to state-level taxation upon receipt. However, it is vital to understand that this exemption applies specifically to Florida’s state taxes. Federal tax laws still govern a portion of large estates, and certain types of inherited assets may have their own tax considerations at both the federal and state levels, even if no direct inheritance or estate tax is levied.

The Absence of Florida Estate and Inheritance Taxes
Historically, Florida has chosen not to implement a state-level estate tax. An estate tax is levied on the total value of a deceased person’s assets before they are distributed to beneficiaries. Similarly, an inheritance tax is a tax on the beneficiary’s right to receive inherited property, often varying based on the relationship between the deceased and the beneficiary. In Florida, neither of these taxes is applicable. This means that if an individual passes away a resident of Florida, their estate will not be subject to a tax calculated on its total value by the state. This can significantly simplify the inheritance process and preserve more wealth for heirs.
Federal Estate Tax Considerations
While Florida offers a tax-free inheritance at the state level, federal estate taxes are a separate consideration. The federal estate tax applies only to very large estates. For the year 2024, the federal estate tax exemption is set at $13.61 million per individual. This means that an individual can pass on assets valued up to this substantial amount without incurring federal estate tax. For married couples, this exemption can effectively be doubled if proper estate planning, such as portability elections, is utilized. Therefore, only estates exceeding this high threshold will be subject to federal estate tax. The tax rate for the portion of the estate above the exemption is progressive, with the highest marginal rate being 40%.
Income Tax on Inherited Assets
Beyond estate and inheritance taxes, it is essential to distinguish these from income taxes. Inherited assets themselves are generally not considered taxable income by the IRS at the time of inheritance. However, any income generated by these assets after they are inherited can be subject to income tax. For example, if you inherit stocks, the dividends you receive from those stocks after taking ownership are taxable income. If you inherit a rental property, the rental income you collect is taxable. Similarly, if you inherit a retirement account, such as a traditional IRA or a 401(k), withdrawals from these accounts are typically taxed as ordinary income, though the specific rules for inherited retirement accounts have evolved with recent legislation.
Specific Asset Types and Their Tax Implications in Florida
While Florida itself does not tax inheritances, the nature of the inherited asset can trigger taxability at the federal level or as ongoing income. Understanding these nuances is key to managing your inherited wealth effectively.
Inherited Real Estate
Real estate is a common form of inheritance. In Florida, inheriting a property does not trigger a state inheritance or estate tax. However, there are several important considerations. Firstly, the property’s value at the time of the deceased’s death is generally stepped up to its fair market value. This means that when you eventually sell the property, your capital gains tax will be calculated based on the difference between the selling price and this stepped-up basis, not the original purchase price by the deceased. This “step-up in basis” is a significant tax benefit. Property taxes, however, are an ongoing expense for the owner of the real estate, and these are levied by local county governments in Florida.
Inherited Financial Assets (Stocks, Bonds, Mutual Funds)
Similar to real estate, inherited stocks, bonds, and mutual funds benefit from the step-up in basis. When the beneficiary inherits these assets, their cost basis is adjusted to the fair market value on the date of the decedent’s death. This can significantly reduce or eliminate capital gains tax if the assets are sold shortly after inheritance. Any dividends or interest earned by these assets after the inheritance are considered taxable income to the beneficiary.
Inherited Retirement Accounts (IRAs, 401(k)s)
The tax treatment of inherited retirement accounts has seen significant changes with the SECURE Act. Generally, beneficiaries are now required to withdraw the entire balance of an inherited traditional IRA or 401(k) within 10 years of the original account owner’s death. These withdrawals are considered taxable ordinary income to the beneficiary. Roth IRAs, on the other hand, are generally tax-free upon withdrawal for beneficiaries, as the contributions were made with after-tax dollars. Spousal beneficiaries often have more flexibility, with options to roll over the inherited IRA into their own account or treat it as their deceased spouse’s IRA. Non-spousal beneficiaries must adhere to the 10-year distribution rule.
Inherited Life Insurance Policies
Life insurance proceeds paid to a named beneficiary are typically received income tax-free at both the federal and state levels. This is a common estate planning tool designed to provide immediate financial support to beneficiaries without tax burdens. This exemption generally applies whether the policy was owned by the deceased or by an irrevocable life insurance trust.
Estate Planning Strategies to Minimize Tax Burdens
Even with Florida’s favorable tax laws, prudent estate planning can ensure that your assets are passed to your loved ones with maximum efficiency and minimal tax implications.
The Role of a Will and Trusts
A properly drafted will ensures that your assets are distributed according to your wishes. While a will doesn’t directly affect inheritance taxes in Florida (as there are none), it is crucial for directing the distribution of assets and can help avoid probate, which can be a time-consuming and costly process. Trusts, such as revocable living trusts or irrevocable trusts, can offer additional benefits. Revocable living trusts allow for asset management during your lifetime and seamless transfer to beneficiaries upon your death, often avoiding probate altogether. Irrevocable trusts can be used for more advanced estate planning, potentially removing assets from your taxable estate for federal estate tax purposes if structured correctly and if your estate is large enough to warrant such planning.
Gifting Strategies
While not directly related to inheritance taxes in Florida, lifetime gifting can be a strategy to reduce the size of your taxable estate for federal purposes. Individuals can gift up to the annual exclusion amount ($18,000 per recipient in 2024) without using any of their lifetime gift tax exemption. Gifts exceeding this annual amount will use a portion of the individual’s lifetime gift tax exemption, which is unified with the estate tax exemption. For Floridians whose estates are unlikely to approach the federal exemption threshold, lifetime gifting is more about sharing wealth during one’s lifetime than a strategy to avoid state-level inheritance taxes.
Professional Advice for Inheritance and Taxation
Given the complexities involved, particularly concerning federal tax laws and the nuances of different asset types, seeking advice from qualified professionals is highly recommended. An estate planning attorney can help draft wills and trusts, and a certified public accountant (CPA) or tax advisor can provide guidance on income tax implications and federal estate tax planning. They can help ensure that your estate plan aligns with your financial goals and effectively transfers your assets to your beneficiaries. For those considering luxury accommodations or upscale resorts for a celebratory trip after receiving an inheritance, consulting with financial advisors can also help in budgeting and making informed decisions about how to best enjoy their newfound wealth. This could include exploring exclusive properties such as The Breakers Palm Beach or planning a sophisticated getaway to Miami.
In conclusion, while Florida does not levy state inheritance or estate taxes, understanding the broader financial implications, including federal estate tax and ongoing income tax obligations on inherited assets, is paramount. Proper planning and professional guidance are essential for navigating these matters and ensuring a smooth and tax-efficient transfer of wealth.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.