
The landscape of auto insurance can often feel like navigating a labyrinth of legal jargon and policy details. For residents of the Golden State, one coverage option that frequently sparks discussion and inquiry is Uninsured Motorist Bodily Injury (UMBI) coverage. The question itself, “Is Uninsured Motorist Bodily Injury Necessary in California?”, is not a simple yes or no. Instead, it delves into a crucial aspect of financial protection for drivers and their passengers in a state known for its vast road network and diverse driving population. Understanding the nuances of UMBI, its legal standing in California, and its practical implications is paramount for making informed decisions about one’s insurance policy.
Understanding Uninsured Motorist Bodily Injury Coverage
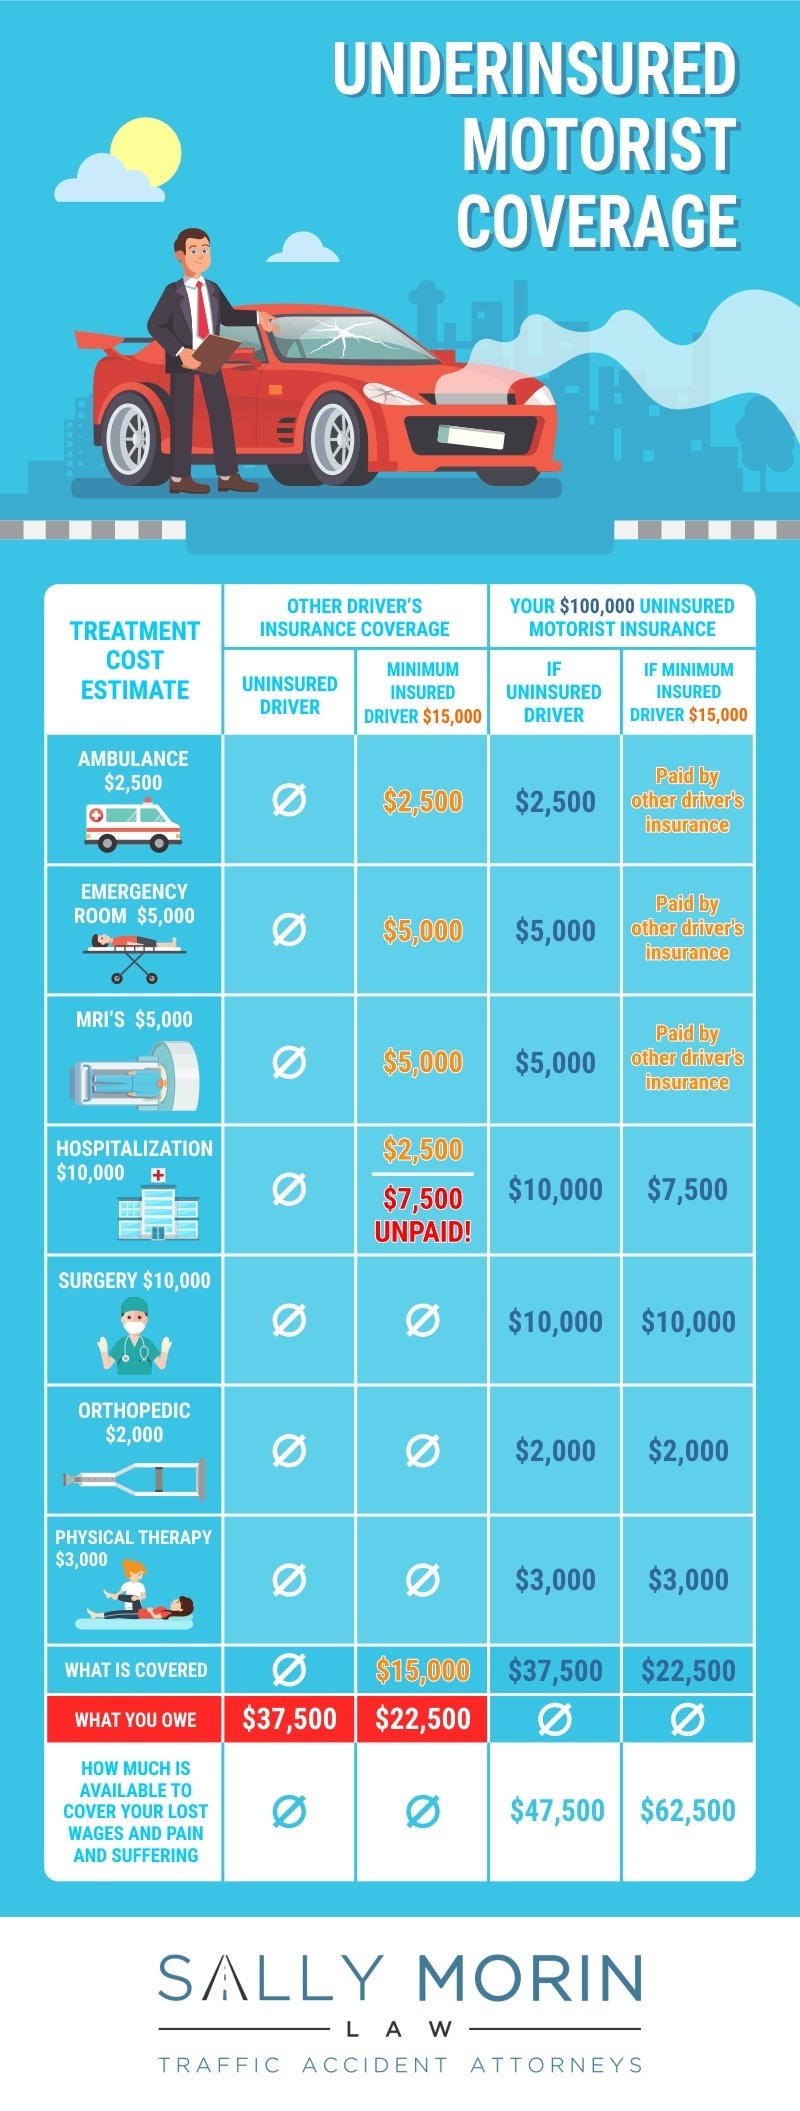
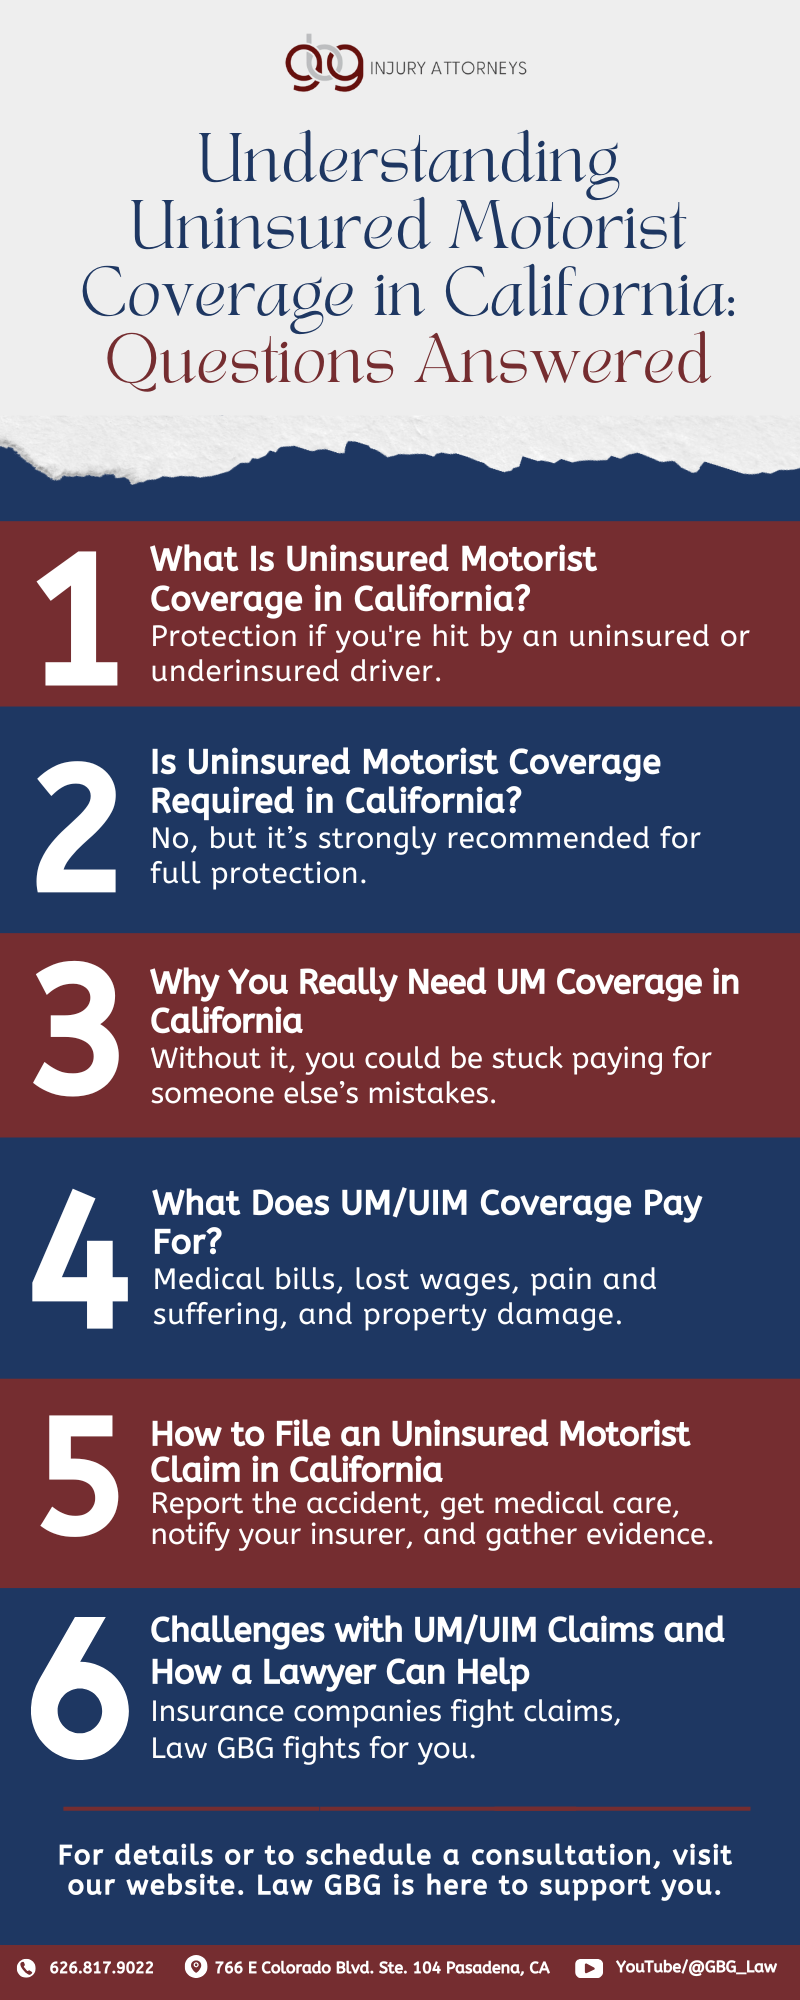
At its core, Uninsured Motorist Bodily Injury coverage is designed to protect you and your passengers in the unfortunate event that you are involved in an accident caused by a driver who does not have any auto insurance, or who has insufficient insurance to cover your medical expenses. This coverage essentially steps in to fill the financial gap left by the at-fault, uninsured driver.
What UMBI Covers
UMBI coverage is specifically for bodily injury. This means it can help pay for:
- Medical Expenses: This includes ambulance rides, hospital stays, doctor’s visits, surgeries, diagnostic tests, and any other necessary medical treatment resulting from the accident.
- Lost Wages: If your injuries prevent you from working, UMBI can help compensate for the income you lose during your recovery period.
- Pain and Suffering: In many cases, UMBI can also cover compensation for the physical pain, emotional distress, and overall suffering you endure due to the injuries sustained in the accident.
- Rehabilitation Costs: This can include physical therapy, occupational therapy, and other forms of rehabilitation needed to regain your health and mobility.
It is important to distinguish UMBI from Uninsured Motorist Property Damage (UMPD) coverage, which, when available and chosen, covers damage to your vehicle caused by an uninsured driver. In California, UMPD is generally not offered on its own; instead, it’s often bundled with comprehensive and collision coverage, or is part of a broader uninsured motorist coverage.
The Legal Mandate in California
In California, all drivers are legally required to carry a minimum level of liability insurance. This liability coverage is intended to pay for damages and injuries you cause to others if you are at fault in an accident. However, this legal requirement does not guarantee that all drivers on the road will comply with the law.
The state of California also has specific requirements regarding Uninsured Motorist coverage. While UMBI coverage is not strictly mandatory in the same way that liability insurance is, insurance providers are required to offer it to policyholders. If you choose to reject UMBI coverage, you must do so in writing. This written rejection signifies your understanding of the risks associated with foregoing this protection. The rationale behind this requirement to offer is to ensure that drivers are at least presented with the option to protect themselves from the financial fallout of accidents involving uninsured motorists, acknowledging the prevalence of uninsured drivers on California roads.
The Prevalence of Uninsured Drivers in California
The necessity of UMBI coverage is directly tied to the statistical reality of uninsured drivers. While California has robust laws mandating insurance, a significant percentage of drivers still operate vehicles without it.
Statistics and Realities
According to various studies and reports, California consistently ranks among the states with a higher-than-average percentage of uninsured drivers. Factors contributing to this include the high cost of insurance premiums in the state, the sheer volume of vehicles on the road, and a segment of the population that may intentionally choose to drive uninsured due to financial constraints or a disregard for the law.
When you are involved in an accident with an uninsured driver, and you do not have UMBI coverage, you are left with very limited recourse. You would essentially have to pursue legal action against the uninsured driver directly. However, drivers who cannot afford insurance are often also individuals with limited assets or income, making it extremely difficult, if not impossible, to recover any significant financial compensation through a lawsuit, even if you win. This leaves you responsible for your own medical bills, lost wages, and other accident-related expenses, even though the accident was not your fault.

The “Hit-and-Run” Scenario
Another critical aspect of uninsured driving, which underscores the importance of UMBI, is the prevalence of hit-and-run accidents. Unfortunately, in many collisions, the at-fault driver flees the scene, making it impossible to identify them or their insurance information. In such cases, if you lack UMBI coverage, you are once again left to bear the financial burden of your injuries. UMBI coverage is often the only form of protection available in these unfortunate circumstances, ensuring that your medical needs are addressed even when the responsible party cannot be identified.
When UMBI Proves Invaluable
The true value of Uninsured Motorist Bodily Injury coverage becomes apparent when you consider various scenarios where it can provide essential financial relief.
Accidents Caused by Negligent Uninsured Drivers
Imagine this common scenario: You are driving through a busy intersection in Los Angeles or perhaps on a scenic route near San Francisco, obeying all traffic laws. Suddenly, another vehicle runs a red light or makes an illegal turn, colliding with your car. You and your passengers sustain injuries. Upon exchanging information, you discover the at-fault driver has no insurance. Without UMBI, your options are bleak: either pay for your medical treatment out-of-pocket or hope to recover funds from someone who has already demonstrated an inability to meet basic legal requirements. With UMBI, your own insurance policy steps in to cover your medical bills and lost wages up to your policy limits, providing a critical safety net.
Underinsured Motorist Situations
It is also important to note that UMBI coverage often extends to situations involving underinsured motorists. This means if the at-fault driver has insurance, but their policy limits are too low to cover the full extent of your damages and injuries, your UMBI coverage can supplement the difference. For instance, if the at-fault driver has the minimum liability coverage required by California, which might be $15,000 per person, but your medical bills amount to $50,000, your UMBI coverage can help pay the remaining $35,000, provided your policy has adequate limits. This is often referred to as Underinsured Motorist Bodily Injury (UIMBI) coverage, and it is frequently bundled with UMBI.
Protecting Your Passengers
UMBI coverage is not just about protecting yourself; it’s also about ensuring the well-being of your passengers. If you have friends or family members riding with you, and an uninsured driver causes an accident, your UMBI coverage can help pay for their injuries as well. This broadens the protective scope of the coverage, offering peace of mind when you are responsible for the safety of others.
Deciding on UMBI Coverage Limits and Rejection
Given the significant benefits, the decision to carry UMBI coverage, and the amount of coverage to select, is a critical one for California drivers.
Choosing Appropriate Limits
When selecting UMBI coverage, consider the potential costs of medical treatment and lost income. Medical expenses can quickly escalate, especially in cases of severe injury. It is generally advisable to choose UMBI limits that are at least as high as your own liability coverage limits. This ensures that you are adequately protected in situations where the at-fault driver is uninsured or underinsured, mirroring the level of protection you provide to others. Many insurance agents recommend UMBI limits that align with the average cost of healthcare in California, which can be substantial.
The Risks of Rejection
While California law requires insurers to offer UMBI and allows for written rejection, understanding the implications of such a rejection is vital. By rejecting UMBI coverage, you are essentially self-insuring against the possibility of being injured by an uninsured or underinsured driver. This means you would be responsible for all your medical expenses, lost wages, and pain and suffering resulting from such an accident. For most drivers, especially those who rely on their vehicle for daily life or work, the financial risk associated with rejecting UMBI is often too great to justify the premium savings.
In conclusion, while not a legal mandate to purchase, Uninsured Motorist Bodily Injury coverage is a vital component of a comprehensive auto insurance policy in California. The prevalence of uninsured drivers, combined with the potentially catastrophic financial consequences of an accident, makes UMBI a wise and often necessary investment for protecting yourself, your passengers, and your financial future on the road.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.