
Navigating the complexities of healthcare billing in Florida can often feel like deciphering a foreign language, especially when it comes to understanding how copays and subsequent bills interact. For residents and visitors alike, the expectation after paying a copay at a Florida doctor’s office is that their financial obligation for that specific visit has been met. However, the reality is often more nuanced. This article delves into the circumstances under which a Florida doctor might indeed bill you for more than your initial copay, exploring the factors that contribute to these additional charges and how patients can protect themselves.

Understanding the Role of Copays in Florida Healthcare
A copay, or copayment, is a fixed amount that you pay for a covered healthcare service after you’ve paid your deductible. It’s a common feature of many health insurance plans, designed to share the cost of care between the insurer and the insured. In Florida, as elsewhere, copays typically apply to specific services, such as doctor’s office visits, specialist appointments, and prescription drugs.
The Copay as a Predictable Expense
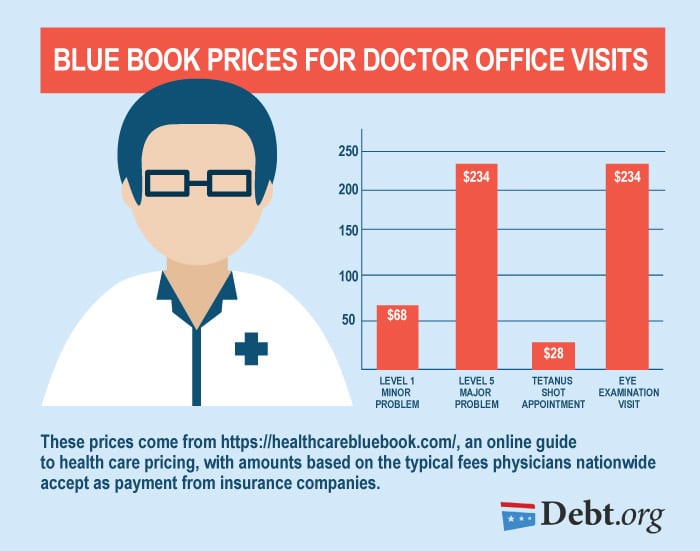
The primary appeal of a copay system for patients is its predictability. When you book an appointment with a Florida physician, you generally know what to expect to pay out-of-pocket at the time of service. For instance, a routine check-up might have a $30 copay, while a visit to a specialist like a cardiologist could be $75. This upfront payment helps manage household budgets and avoids the surprise of a large bill arriving weeks later for a service whose cost was seemingly settled at the front desk.
Types of Services and Their Copay Structures
It’s crucial to understand that copay structures can vary significantly depending on your insurance plan and the type of service received.
- Primary Care Physician (PCP) Visits: These often have lower copays, reflecting their role in general health maintenance.
- Specialist Visits: Appointments with specialists, such as dermatologists, endocrinologists, or neurologists, typically incur higher copays due to the specialized nature of their services.
- Emergency Room Visits: These usually have the highest copays among office-based services, and often come with deductibles and coinsurance as well.
- Urgent Care Centers: Copays for urgent care facilities often fall between PCP and specialist visit copays, offering a middle ground for non-life-threatening conditions.
- Diagnostic Tests and Procedures: While some basic tests performed during a visit might be covered by the copay, more complex lab work or imaging (like X-rays or MRIs) may be subject to deductibles, coinsurance, or separate billing from the facility or the radiologist.
In Florida, understanding these distinctions before seeking care is a proactive step in managing potential costs.
Beyond the Copay: Reasons for Additional Billing
While your copay signifies your payment for a specific service at the time of your visit, it does not always represent the total cost of your medical encounter. Several factors can lead to a Florida doctor billing you more after your initial copay has been paid.
1. Deductibles and Coinsurance
Perhaps the most common reason for post-copay billing is the unmet deductible or the application of coinsurance.
Understanding Deductibles
A deductible is the amount you must pay out-of-pocket for covered healthcare services before your insurance plan starts to pay. Many Florida health insurance plans have deductibles, especially for more comprehensive services or when you see an out-of-network provider. If you haven’t met your deductible for the plan year, your insurance company will not pay its share of the cost for services until the deductible is satisfied. This means that the doctor’s office, after receiving your copay, will submit the claim to your insurer. If the service is subject to your deductible, the full billed amount (minus what the insurer would have paid) will become your responsibility until the deductible is met.
The Role of Coinsurance
Coinsurance is your share of the costs of a covered healthcare service, calculated as a percentage (e.g., 20%) of the allowed amount for the service. Unlike a copay, which is a fixed fee, coinsurance is a variable cost that depends on the total bill. Once you’ve met your deductible, you’ll typically pay coinsurance for services until you reach your out-of-pocket maximum for the year. For example, if your coinsurance is 20% and the allowed amount for a procedure after your deductible is met is $1,000, you would owe $200. A Florida physician’s office will bill you for this coinsurance amount after processing your claim through your insurance.
2. Services Not Covered by the Copay
Not every interaction or service provided during a doctor’s visit is necessarily covered by the standard copay.
Ancillary Services and Procedures
When you visit a doctor’s office in Florida, the physician might perform or order services beyond the scope of your initial visit copay. This can include:
- In-office procedures: Minor surgeries, biopsies, or specialized treatments performed by the doctor during your appointment.
- Diagnostic tests: Blood work, X-rays, EKGs, or other tests conducted on-site. While the interpretation of these tests might be included in a specialist’s copay, the technical component or the facility fee for performing them may be billed separately.
- Durable Medical Equipment (DME): If a doctor prescribes a brace, walker, or other medical equipment during your visit, this will typically be billed separately by the DME supplier, not by the doctor’s office as part of the copay.

Out-of-Network Providers
If a Florida doctor’s office is not in your insurance network, your copay might not apply in the traditional sense, or your benefits will be significantly different. You might pay a higher out-of-pocket amount, or your insurance may not cover the visit at all, leading to a bill for the full service cost after paying an initial amount that may not be considered a copay.
3. Incorrect Coding or Billing Errors
Unfortunately, human error can occur in any billing process.
Medical Coding Mistakes
Medical coders translate diagnoses and procedures into standardized codes (like ICD-10 and CPT codes) that are used for billing insurance companies. If a coder mistakenly assigns a code for a more complex or expensive service than what was actually performed, it can lead to an inflated bill. This can happen even after a copay has been collected, as the insurer will process the claim based on the submitted codes.
Administrative Errors
Simple administrative mistakes, such as misapplying payments, entering incorrect patient information, or failing to properly apply insurance benefits, can also result in erroneous bills.
4. Services Rendered by Different Providers Within the Same Facility
In larger medical practices or healthcare systems in Florida, a single visit might involve interactions with multiple healthcare professionals, each potentially billing separately.
Independent Billing by Specialists
A common scenario is when a physician’s office uses an independent laboratory or radiology group for tests. Even if the doctor’s visit itself was covered by your copay, the charges for the lab work or the X-ray interpretation will come from these separate entities, often with their own billing procedures, deductibles, and coinsurance. This is particularly relevant in large medical centers like those found in cities such as Miami or Orlando.
Contracted Services
Some physician groups may contract with other providers for specific services offered within their facility. For example, a cardiology practice might have an independent physical therapist on staff, whose services would be billed separately.
Protecting Yourself: What You Can Do
Understanding these potential charges is the first step in managing your healthcare costs in Florida. Here are practical strategies to avoid unexpected bills.
Before Your Appointment
- Verify Insurance Coverage: Always confirm that your doctor’s office is in your insurance network and that your specific plan covers the services you anticipate needing. Call your insurance provider directly to clarify benefits, deductibles, copays, and coinsurance for different types of visits and procedures.
- Understand Your Plan Details: Familiarize yourself with your insurance policy’s deductible, out-of-pocket maximum, and any specific limitations or exclusions.
- Ask About Potential Extra Costs: When scheduling your appointment, don’t hesitate to ask the office staff about any services that might be billed separately or if there are any procedures commonly performed during such visits that are not covered by the standard copay.
During Your Appointment
- Communicate with Your Doctor: If your doctor recommends a test or procedure, ask whether it’s included in your visit copay or if it will incur additional charges. Inquire about less expensive alternatives if cost is a concern.
- Request an Itemized List of Services: Before leaving the office, ask for a clear list of all services rendered during your visit. This helps ensure accuracy and provides a reference point for future billing.
After Your Appointment
- Review Your Explanation of Benefits (EOB): Your insurance company will send you an EOB detailing what the insurer has paid and what your financial responsibility is. Compare this EOB with the bills you receive from the provider.
- Scrutinize All Bills: Carefully review any bills you receive from the doctor’s office or any other medical entity. Check for accuracy in dates of service, services rendered, and amounts billed.
- Question Discrepancies: If you believe you have been billed incorrectly, do not pay without clarification. Contact the billing department of the provider’s office immediately to discuss your concerns. They should be able to explain the charges and provide documentation.
- Contact Your Insurance Provider: If you cannot resolve a billing issue with the provider, contact your insurance company for assistance. They can help mediate disputes and clarify coverage.
- Understand Your Rights: Florida has laws and regulations governing medical billing and patient rights. Familiarize yourself with these protections, which can include grievance procedures and rights related to surprise medical bills.
In conclusion, while a copay in Florida is intended to be a predictable upfront payment, it’s not always the final word on your financial responsibility for a medical encounter. By understanding your insurance plan, communicating proactively with your healthcare providers, and meticulously reviewing all billing statements, you can navigate the Florida healthcare system more effectively and avoid unwelcome surprises.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.