
Navigating the complexities of estate planning can often feel like charting an unknown territory, especially when considering the specific tax implications of a particular jurisdiction. For residents and those with assets within the state of Oregon, understanding the nuances of the Oregon estate tax is crucial for ensuring their legacy is preserved and passed on efficiently to their beneficiaries. This guide aims to demystify the Oregon estate tax, offering insights into its structure, exemptions, and strategic approaches to minimize its impact. While estate planning is a deeply personal endeavor, seeking professional legal and financial advice tailored to your unique circumstances is always recommended.

Understanding the Oregon Estate Tax Landscape
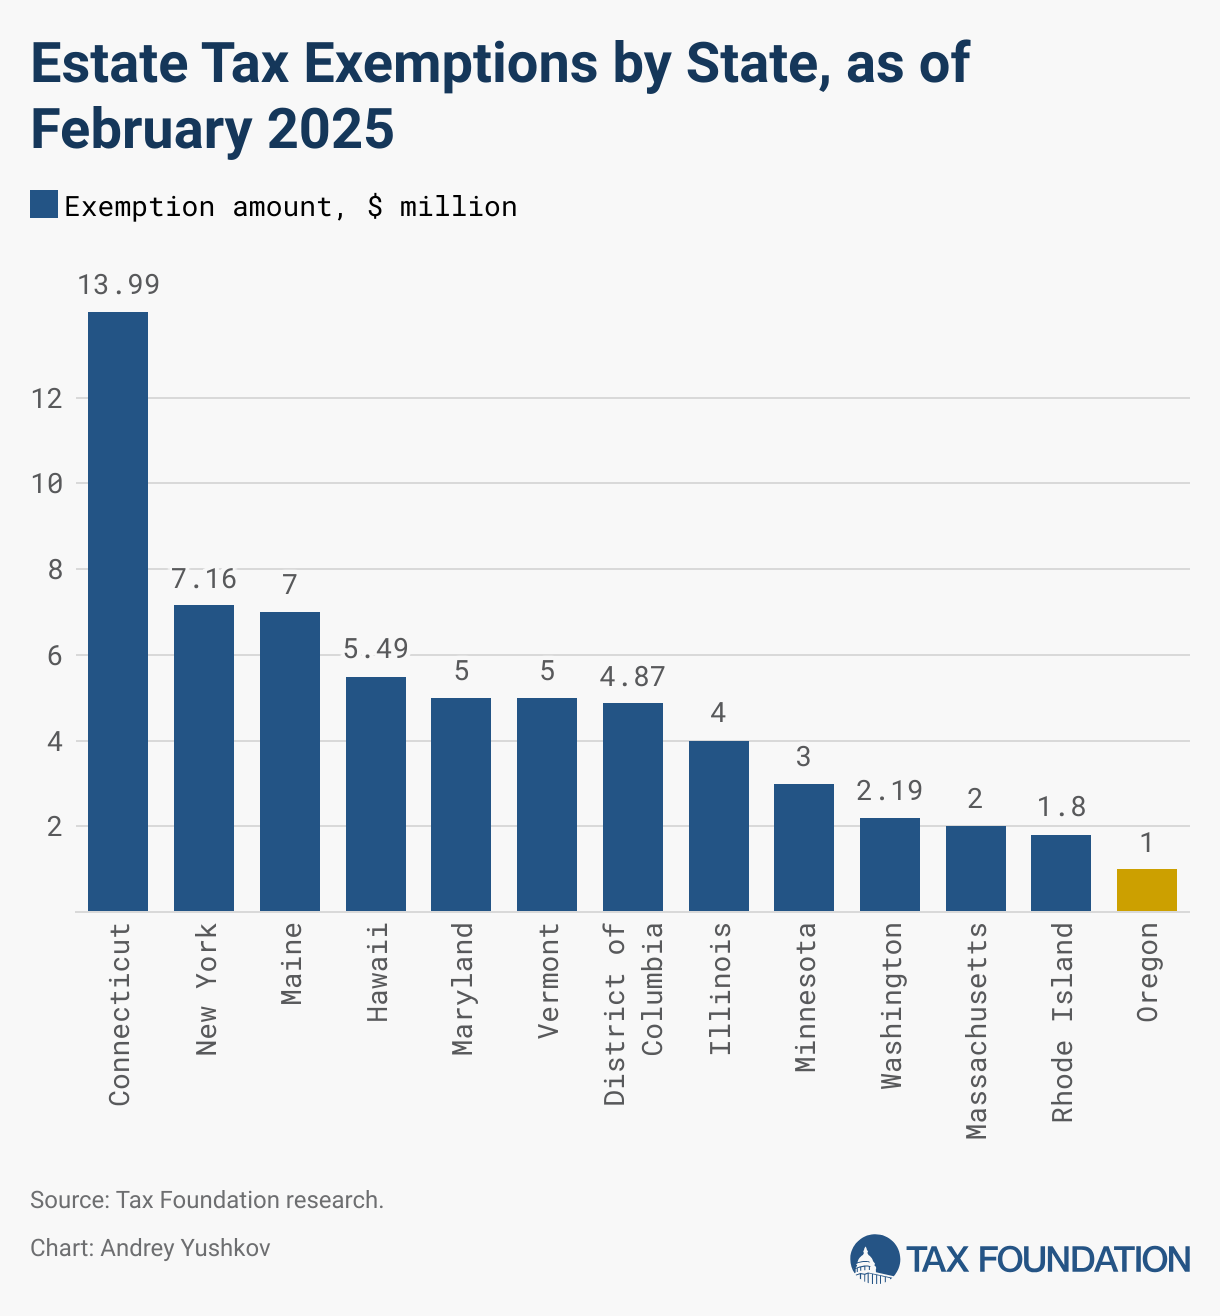
Unlike the federal estate tax, which applies to estates exceeding a very high exemption threshold, the Oregon estate tax has a significantly lower exemption amount. This means that more estates in Oregon are subject to state-level taxation.
Key Differences from Federal Estate Tax
The most significant distinction lies in the exemption amount. The federal estate tax exemption is currently millions of dollars, adjusted annually for inflation. In stark contrast, Oregon’s estate tax exemption is considerably lower, making it a relevant consideration for a broader range of individuals. This lower threshold underscores the importance of proactive planning for Oregon residents.
The Exemption Threshold and Its Impact
As of the most recent legislative updates, the Oregon estate tax exemption is set at a specific dollar amount. Estates valued above this threshold are subject to taxation on the excess amount. It is vital to consult the most current figures, as these can be subject to legislative changes. Understanding this threshold is the first step in determining if your estate may be liable for Oregon estate tax.
How the Tax is Calculated
If an estate exceeds the exemption threshold, the tax is calculated based on a progressive tax rate system. This means that the higher the value of the taxable portion of the estate, the higher the tax rate applied. The rates are applied to the value of the estate that falls within specific tax brackets, above the exemption amount.
Strategies for Minimizing Oregon Estate Tax Liability
Fortunately, there are several strategies that individuals can employ to reduce or eliminate their Oregon estate tax liability. These strategies often involve careful planning and the judicious use of legal and financial tools.
Gifting Strategies
One of the most straightforward methods of reducing an estate’s value is through lifetime gifting. Oregon law, like federal law, allows individuals to make gifts during their lifetime without incurring immediate gift tax. By systematically transferring assets to beneficiaries over time, an individual can reduce the total value of their taxable estate at the time of death.
Annual Gift Exclusion
While Oregon does not have a separate state gift tax, it’s important to be aware of any applicable federal gift tax rules. The federal annual gift tax exclusion allows individuals to gift a certain amount to any number of recipients each year without that gift counting towards their lifetime gift and estate tax exemption. These annual exclusion amounts are adjusted periodically for inflation.
Large Gifts and Their Implications
For larger gifts that exceed the annual exclusion, consideration must be given to the potential impact on the federal lifetime exemption. However, strategically making substantial gifts during one’s lifetime can significantly reduce the taxable estate for Oregon estate tax purposes, provided these gifts are structured appropriately and do not inadvertently trigger other tax liabilities.
Trusts and Their Role in Estate Planning
Various types of trusts can be invaluable tools in estate tax mitigation. Trusts allow for the management and distribution of assets according to the grantor’s wishes, often with significant tax advantages.
Irrevocable Trusts
Irrevocable trusts are a cornerstone of advanced estate planning. Once assets are transferred into an irrevocable trust, they are generally considered removed from the grantor’s taxable estate. This can be particularly effective for reducing Oregon estate tax. Common types of irrevocable trusts used for this purpose include:
- Irrevocable Life Insurance Trusts (ILITs): These trusts own life insurance policies. When the insured dies, the death benefit is paid to the trust, which then distributes it to the beneficiaries, typically free of estate tax.
- Grantor Retained Annuity Trusts (GRATs): These trusts allow the grantor to retain an income stream for a fixed period, with the remainder passing to beneficiaries. If structured correctly, the value of the remainder interest can be significantly reduced for estate tax purposes.
- Dynasty Trusts: These are long-term irrevocable trusts designed to benefit multiple generations, offering robust estate tax protection and asset management.
Revocable Trusts
While revocable trusts do not directly reduce the taxable estate for estate tax purposes (as the assets are still considered owned by the grantor), they offer significant benefits in terms of probate avoidance and asset management. A revocable trust can be a foundational element of a comprehensive estate plan that also incorporates strategies for estate tax reduction.
Charitable Giving
For individuals with philanthropic goals, charitable giving can serve a dual purpose: supporting worthy causes and reducing estate tax liability.

Direct Bequests to Charities
Bequests made directly to qualified charitable organizations are generally deductible from the gross estate for both federal and Oregon estate tax purposes. This means that the value of assets donated to charity is subtracted from the total estate value before any taxes are calculated.
Charitable Remainder Trusts (CRTs) and Charitable Lead Trusts (CLTs)
These split-interest trusts offer sophisticated ways to incorporate charitable giving into estate plans.
- Charitable Remainder Trusts (CRTs): In a CRT, assets are transferred to the trust, providing an income stream to non-charitable beneficiaries for a specified term or for life. Upon the termination of the trust, the remaining assets pass to a designated charity. This structure can provide income tax benefits and reduce the taxable value of the assets passed to non-charitable heirs.
- Charitable Lead Trusts (CLTs): With a CLT, income is paid to a charity for a specified period, after which the remaining assets are distributed to non-charitable beneficiaries. CLTs can be particularly effective in reducing the taxable gift or estate upon the transfer of assets to the trust for the benefit of the remainder beneficiaries.
Strategic Use of Estate Planning Tools
Beyond gifting and trusts, other estate planning tools can contribute to tax efficiency.
Utilizing the Marital Deduction
The unlimited marital deduction allows assets passing from a deceased spouse to a surviving spouse to be exempt from estate tax. This is a fundamental aspect of estate planning for married couples, deferring estate tax until the death of the surviving spouse. However, careful planning is still required to ensure that the surviving spouse’s estate is also managed effectively to avoid future tax burdens.
Bypass Trusts (Credit Shelter Trusts)
For married couples, a bypass trust (or credit shelter trust) can be used to take advantage of both spouses’ estate tax exemptions. Upon the death of the first spouse, a portion of their estate, up to the applicable exemption amount, can be placed into a bypass trust. The surviving spouse can benefit from this trust, but the assets within it are not included in their taxable estate. This strategy effectively doubles the exemption available to the couple.
Planning for Business Succession
For business owners, succession planning is a critical component of estate tax management. The value of a business can represent a significant portion of an estate, and its transfer can trigger substantial tax liability.
Buy-Sell Agreements
These agreements, often used in closely held businesses, can help establish a predetermined value for the business interest. This can prevent disputes among heirs and provide a mechanism for liquidity to pay estate taxes.
Business Valuation and Discounts
Proper valuation of business interests is essential. Certain valuation discounts, such as for lack of marketability or minority interest, may be available, reducing the taxable value of the business. However, these discounts are subject to strict IRS scrutiny.
Employee Stock Ownership Plans (ESOPs)
ESOPs can offer attractive tax benefits for business owners looking to sell their company and for employees. They can facilitate a tax-advantaged transfer of ownership while providing liquidity for the selling owner.
Professional Guidance: The Cornerstone of Effective Planning
While this guide provides an overview of strategies for avoiding Oregon estate tax, it is imperative to remember that estate planning is highly individualized. The effectiveness of any given strategy depends on a multitude of factors, including the size and composition of the estate, the age and health of the individuals involved, family dynamics, and specific financial goals.
The Role of Estate Attorneys
Experienced estate planning attorneys are indispensable in this process. They can:
- Advise on the latest Oregon and federal tax laws.
- Draft complex trust documents and wills.
- Ensure that estate plans are legally sound and achieve the desired outcomes.
- Help navigate the intricacies of probate and estate administration.
Financial Advisors and Tax Professionals
Financial advisors play a crucial role in assessing asset values, projecting future financial needs, and implementing investment strategies that align with estate planning goals. Tax professionals can provide expert advice on income tax implications, gift tax considerations, and the most tax-efficient ways to structure transactions.
Regular Review and Updates
Estate plans are not static documents. Life events, changes in tax laws, and evolving financial circumstances necessitate periodic reviews and updates. It is recommended to revisit your estate plan at least every three to five years, or whenever significant life changes occur, such as marriage, divorce, birth of a child, or acquisition of substantial assets. Proactive and consistent review ensures that your estate plan remains effective in protecting your legacy and minimizing tax burdens for your loved ones.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.