
The insurance landscape in Florida has long been a subject of concern for residents and businesses alike, a turbulent sea of rising premiums, limited coverage options, and the persistent specter of insurer insolvency. Amidst this ongoing volatility, whispers have begun to circulate regarding the potential departure of another significant player from the state’s market: Frontline Insurance. Such a move, if realized, could send further shockwaves through an already strained system, impacting homeowners, renters, and indeed, the broader tourism and hospitality sectors that are so vital to the Sunshine State’s economy. This article delves into the potential implications of Frontline Insurance withdrawing from Florida, exploring the factors driving such decisions and the cascading effects on the state’s unique ecosystem.

Understanding the Shifting Sands of Florida’s Insurance Market
Florida’s insurance market is a complex tapestry woven with the threads of natural disasters, regulatory challenges, and the inherent risks associated with its coastal geography. The state experiences a disproportionate number of hurricanes, leading to significant claims payouts that strain the financial reserves of insurance companies. This, coupled with issues such as widespread litigation and sinkhole activity, creates a high-risk environment that many insurers find increasingly untenable.
The Role of Catastrophe Exposure
The primary driver behind insurer retrenchment in Florida is undoubtedly its extreme exposure to catastrophic events. The devastating impact of hurricanes like Andrew, Wilma, and more recently, Ian, has resulted in billions of dollars in insured losses. For insurance companies, particularly those that are not adequately reinsured or capitalized, these events can pose an existential threat. Consequently, insurers constantly re-evaluate their risk appetite, often scaling back their exposure in high-risk areas or withdrawing entirely.
Regulatory Environment and Legal Climate
Beyond the natural perils, Florida’s regulatory environment and legal climate have also contributed to market instability. A history of legislative reforms aimed at addressing insurance fraud and litigation has had mixed results. Some argue that reforms have not gone far enough, while others contend that they have created a more hostile environment for insurers through increased legal costs and unpredictable outcomes in court. The state’s Citizens Property Insurance Corporation, a state-backed insurer of last resort, has grown substantially as private insurers have withdrawn, highlighting the shrinking private market.
Financial Health of Insurers
The financial health of insurance companies operating in Florida is under constant scrutiny. Insurers must maintain sufficient capital reserves to pay claims, especially after major disasters. When a company experiences significant losses and its capital is depleted, it may be placed under regulatory supervision or even declared insolvent. This uncertainty forces insurers to make difficult decisions about their market participation.
Potential Impact on Florida’s Tourism and Hospitality Industry
The implications of Frontline Insurance potentially pulling out of Florida extend far beyond individual homeowners. The state’s vibrant tourism and hospitality sector, a linchpin of its economy, could experience significant ripple effects. Hotels, resorts, vacation rental properties, and the myriad of businesses that cater to tourists all rely on robust and affordable insurance coverage to operate.
Increased Insurance Costs for Businesses
If Frontline Insurance, or other insurers, reduce their presence, the demand for insurance from the remaining carriers will likely increase. This heightened demand, coupled with the existing risks, could drive up insurance premiums for hotels, restaurants, tour operators, and other tourism-dependent businesses. These increased operating costs may eventually be passed on to consumers in the form of higher prices for accommodations, activities, and dining experiences.
Impact on Investment and Development
A challenging insurance market can also deter new investment and development within the tourism sector. Potential investors may be hesitant to commit capital to new hotels, attractions, or other tourism infrastructure if they anticipate difficulty in securing adequate and affordable insurance. This could stifle growth and innovation, hindering the long-term competitiveness of Florida as a premier tourist destination. Consider the impact on the development of new theme park attractions in Orlando or new beachfront resorts along the Gulf Coast if insurance costs become prohibitive.
Affordability and Accessibility of Travel
For travelers, the ultimate consequence of a strained insurance market can be reduced affordability and accessibility. If the cost of operating tourism businesses rises significantly due to insurance premiums, these costs will likely be reflected in the prices of flights, accommodations, and activities. This could make Florida a less attractive or more expensive destination for budget-conscious travelers, potentially impacting visitor numbers and the overall economic benefits derived from tourism. This is particularly concerning for a state that relies heavily on drawing visitors from across the United States and internationally to its world-renowned theme parks like Walt Disney World and Universal Orlando Resort, and its beautiful beaches.
What This Means for Homeowners and Travelers
The potential withdrawal of insurers like Frontline Insurance creates a more precarious situation for Florida residents. Homeowners are already grappling with the challenge of finding and affording homeowners insurance.
Limited Choices and Rising Premiums
If insurers exit the market, the choices available to homeowners will shrink further. This lack of competition typically leads to higher premiums. For many Floridians, particularly those in coastal areas or those with older homes, obtaining insurance at a reasonable cost has become a significant financial burden. The prospect of more insurers pulling out only exacerbates this problem, pushing more residents towards the state-backed Citizens Property Insurance Corporation, which can also lead to increased assessments for policyholders.
The Ripple Effect on Short-Term Rentals and Vacation Stays
The vacation rental market, a significant component of Florida’s tourism industry, also relies heavily on insurance. Owners of vacation homes and condominiums in popular destinations like Miami, Key West, and the Florida Keys need specific coverage for short-term rentals, which can be more expensive than traditional homeowners insurance. If insurers withdraw from this segment or drastically increase rates, it could impact the availability and cost of short-term rentals, affecting both property owners and the tourists who book them. This could lead to fewer available properties on platforms like Airbnb or Vrbo, and higher nightly rates for travelers planning a Florida vacation.
Navigating the Future of Florida’s Insurance Market
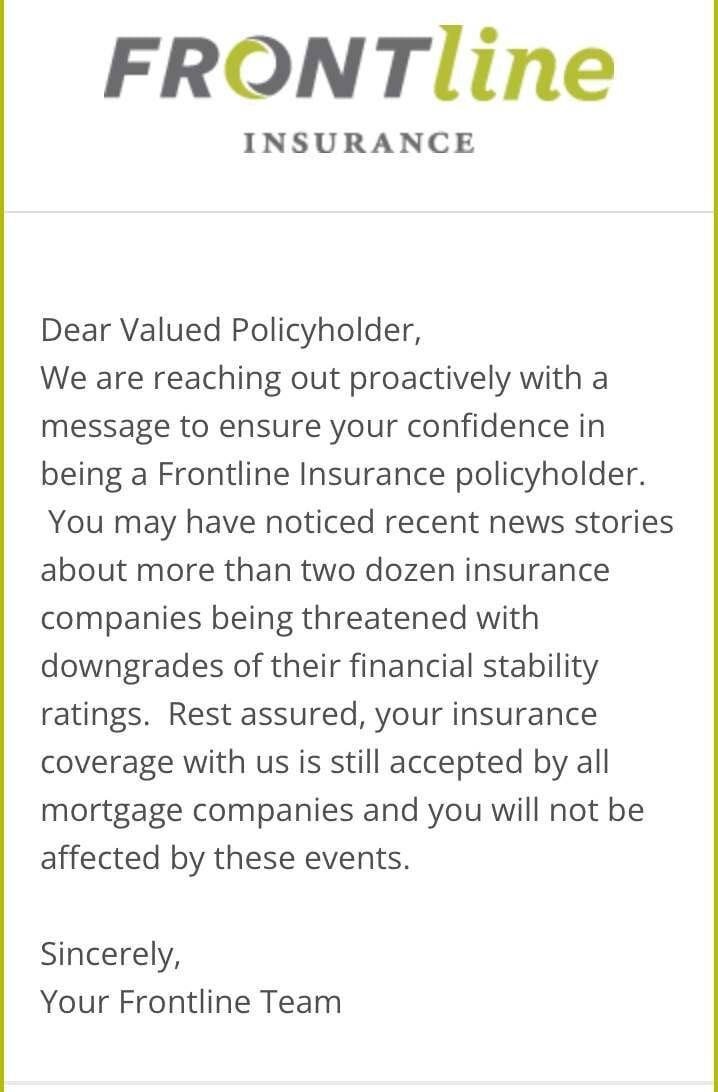
The question of whether Frontline Insurance will indeed pull out of Florida remains a critical one for the state’s economy. The decisions of individual insurance companies are often dictated by a complex interplay of financial realities, risk assessments, and regulatory conditions.
Potential Government Interventions and Reforms
In response to ongoing market instability, Florida lawmakers have explored various avenues for reform. These have included efforts to reduce litigation, promote competition, and provide financial backstops for insurers. The effectiveness and sustainability of these reforms are subject to ongoing debate and evaluation. However, continued insurer retrenchment will likely put additional pressure on state officials to find more comprehensive solutions.
The Importance of Resilient Tourism Infrastructure
For the tourism sector, adaptability and resilience are paramount. Businesses that can diversify their offerings, implement robust risk management strategies, and maintain strong relationships with their insurers may be better positioned to weather market fluctuations. Travelers, in turn, may need to factor insurance-related costs and potential policy limitations into their vacation planning, especially for longer stays or properties in high-risk zones. The long-term viability of Florida’s status as a top tourist destination hinges on finding a sustainable balance between risk and affordability in its insurance market, ensuring that iconic attractions like the Everglades National Park and the vibrant cultural scene of cities like Tampa remain accessible and thriving.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.