
Navigating the intricacies of healthcare billing, particularly in a vibrant state like Florida, can often feel like deciphering a complex map. One common point of confusion for patients revolves around the concept of copays and whether a healthcare provider can levy additional charges beyond this initial payment. This article aims to shed light on the specific regulations and common practices in Florida concerning doctor’s fees after a copay has been rendered, focusing on the patient’s perspective and rights within the United States healthcare system.
Understanding the Copay: A Patient’s Initial Contribution
A copay, or copayment, is a fixed amount that a health insurance policyholder agrees to pay for a covered healthcare service at the time of service. It’s a crucial component of most health insurance plans, designed to share the cost of care between the insurer and the insured. For instance, a patient might have a $25 copay for a primary care visit and a $50 copay for a specialist visit. This payment is typically made at the doctor’s office before the patient sees the physician.

The Role of Insurance in Copay Determination
The amount of your copay is determined by the terms of your specific health insurance plan. Insurance companies categorize services and assign different copay amounts to each. Common examples include:
- Primary Care Physician (PCP) Visits: Often the lowest copay.
- Specialist Visits: Typically a higher copay than PCP visits.
- Emergency Room (ER) Visits: Usually the highest copay, and often waived if the patient is subsequently admitted to the hospital.
- Urgent Care Visits: Generally falls between PCP and ER copays.
- Diagnostic Services: Such as X-rays or lab tests, may have separate copays or be subject to deductibles.
- Prescription Drugs: Copays vary significantly based on drug tier (generic, preferred brand, non-preferred brand, specialty).
It is essential for patients to understand their insurance plan’s formulary and benefit details. This information is usually available on the insurance company’s website or through their customer service. For those visiting Florida for leisure or business, especially if they have insurance from another state, it’s vital to confirm coverage and copay requirements before seeking medical attention. This proactive approach can prevent unexpected financial burdens.
Copays vs. Deductibles vs. Coinsurance
To fully grasp the copay’s function, it’s helpful to distinguish it from other common out-of-pocket costs:
- Deductible: This is the amount you must pay for covered healthcare services before your insurance plan starts to pay. For example, if you have a $1,000 deductible, you’ll pay the first $1,000 of your medical expenses out-of-pocket. Once you meet your deductible, your insurance plan begins to pay its share of the costs. Copays sometimes apply before or after the deductible is met, depending on the plan.
- Coinsurance: After you’ve met your deductible, you might still have to pay a portion of the cost of your medical care. This is called coinsurance. For example, your insurance might pay 80% of the cost of a covered service after you meet your deductible, and you’d pay the remaining 20%.
The copay, in contrast, is a fixed fee that is usually paid regardless of whether the deductible has been met or not, for specific services.
When Additional Charges Might Arise: Beyond the Copay
In most standard healthcare scenarios, the copay is intended to be the patient’s primary financial responsibility at the point of service for a physician’s visit, with the insurance company covering the remaining allowed amount after any applicable deductible or coinsurance. However, there are circumstances where a Florida doctor might indeed charge more than just the copay. These situations often stem from the nature of the services rendered, the patient’s insurance status, or specific contractual agreements.
Services Not Covered by the Copay
The most common reason for additional charges is when services provided during a visit are not covered by the standard copay. A copay typically covers the physician’s consultation and basic examination. If a patient requires additional procedures, tests, or treatments during that same visit, these may incur separate charges.
- Diagnostic Tests: If a doctor orders an X-ray, an ultrasound, blood work, or an MRI in their office, these tests usually have their own associated costs, which might be subject to your deductible and coinsurance, or a separate copay depending on your plan.
- Procedures: Minor surgical procedures, such as mole removal, joint injections, or wound stitching, performed in the doctor’s office, are often billed separately from the office visit itself.
- Supplies and Medications: If the doctor administers a medication, uses specialized medical supplies, or provides a durable medical equipment (DME) item during the visit, these will likely be billed additionally.
- Therapies: Physical therapy, occupational therapy, or speech therapy sessions, even if conducted at the doctor’s office, are typically billed separately and may have different copay or coinsurance structures.
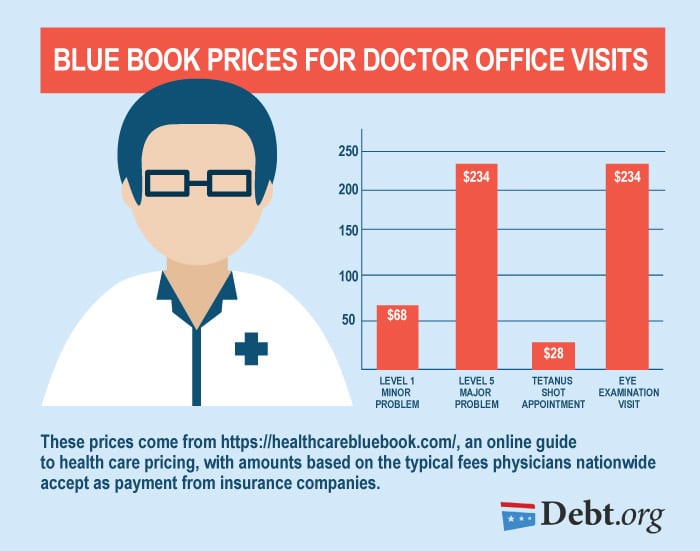
It is crucial for patients to ask their doctor or the medical staff about any potential additional charges before agreeing to a service that seems beyond a standard consultation.
Out-of-Network Providers and Non-Covered Services
Another significant factor is whether the doctor is in-network or out-of-network with the patient’s insurance plan.
- In-Network Providers: When a doctor is part of your insurance network, you generally pay your contracted copay, deductible, and coinsurance. The insurance company has a negotiated rate with these providers.
- Out-of-Network Providers: If a doctor is not in your insurance network, your copay may not apply in the same way, or at all. You might be responsible for the full, non-negotiated cost of the service, or your insurance might cover a smaller percentage, leading to higher out-of-pocket expenses. In some cases, an out-of-network provider might bill you directly for a higher amount, and you would then seek reimbursement from your insurance company, if applicable.
- Non-Covered Services: Some treatments or procedures may simply not be covered by your insurance plan, regardless of whether the provider is in-network. In such cases, you would be responsible for the full cost of these services.
Balance Billing and Surprise Bills
A particularly concerning issue can be “balance billing.” This occurs when an out-of-network provider bills the patient for the difference between their full charge and the amount their insurance company has paid. In Florida, recent legislation aims to protect consumers from surprise medical bills, particularly in emergency situations and for certain non-emergency services performed by out-of-network providers at in-network facilities. However, understanding the nuances of these laws and your rights is essential. For instance, if you receive care at an in-network hospital but a non-participating anesthesiologist or radiologist provides services, you may be protected from balance billing for those services. It’s important to verify the specific protections applicable to your situation.
Patient Rights and Best Practices in Florida
Understanding your rights and adopting proactive communication strategies are key to managing healthcare costs in Florida.
Understanding Your Explanation of Benefits (EOB)
After you receive medical services, your insurance company will send you an Explanation of Benefits (EOB). This document details what services were provided, the total charges, what your insurance plan paid, and what you owe. It is crucial to review your EOB carefully and compare it to the bill you receive from your doctor’s office. Discrepancies can occur, and it’s your responsibility to identify and address them.
Communication is Key: Before and After the Visit
- Before Your Appointment: When scheduling an appointment, ask the office staff to verify your insurance coverage and any expected copay or patient responsibility for the services you anticipate receiving. If you have a complex medical condition or anticipate needing multiple services, it’s wise to have a more detailed conversation.
- During Your Visit: If a doctor suggests a test, procedure, or treatment that you were not expecting or that seems like it might incur additional costs beyond your copay, don’t hesitate to ask: “Will this be covered by my copay, or will there be an additional charge?” and “Can you provide an estimate for the cost of this service?”
- After Your Visit: Review any bills you receive promptly. If you believe you have been overcharged or billed incorrectly, contact the doctor’s billing department immediately. Be prepared to reference your EOB and explain why you believe there is an error. If you cannot resolve the issue with the provider, you can contact your insurance company for assistance.
Legal Protections in Florida
Florida has laws in place to protect patients from certain unexpected medical bills. The No Surprises Act, a federal law, provides significant protections against surprise medical bills for most emergency services and for non-emergency services from out-of-network providers at in-network facilities. If you believe you have been unfairly balance-billed, you have the right to dispute the charge. The Florida Department of Health and the Florida Office of Insurance Regulation are resources that can provide guidance and assistance in navigating these disputes.
Conclusion: Empowering Patients in Healthcare Costs
In conclusion, while a copay serves as the standard upfront payment for many doctor visits in Florida, it is not always the final word on a patient’s financial responsibility. A doctor can indeed charge more after a copay if the services rendered extend beyond what the copay covers, if the patient is seen by an out-of-network provider, or if certain non-covered services are performed.
By understanding the structure of health insurance, the specifics of your plan, and by engaging in clear and consistent communication with your healthcare providers and insurance company, you can better navigate the complexities of medical billing. Proactive questioning, careful review of EOBs and bills, and awareness of your rights as a patient are your most powerful tools in ensuring fair and accurate healthcare charges, whether you are a resident or a visitor to the Sunshine State. For those planning a trip to popular destinations like Miami, Orlando, or the Florida Keys, familiarizing yourself with these principles can add an extra layer of peace of mind to your travels.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.