
Securing a long-term accommodation solution is a significant life milestone, and for many, that means buying their first home. In the vibrant landscape of Arizona, this journey is often made more accessible through a variety of financial credits and assistance programs designed specifically for first-time home buyers. These incentives serve to mitigate common barriers such as down payments, closing costs, and even ongoing mortgage expenses, making the dream of homeownership a tangible reality within this stunning southwestern state. Understanding these credits is crucial for anyone looking to establish a permanent residence in Arizona, whether in a bustling metropolis like Phoenix or a charming community in Tucson.
Understanding First-Time Home Buyer Credits in Arizona
The term “credits” for first-time home buyers in Arizona encompasses a broad range of financial benefits. These are not always direct cash payments but can include down payment assistance, favorable loan terms, and tax credits that reduce overall housing costs. The primary goal of these programs is to stimulate homeownership by making it more affordable and sustainable for individuals and families who are new to the housing market.
Defining a First-Time Home Buyer
Before delving into specific programs, it’s important to clarify what constitutes a “first-time home buyer” in the eyes of most assistance programs. Generally, an individual is considered a first-time home buyer if they have not owned a primary residence in the past three years. This definition can vary slightly by program, but it’s a common benchmark. This broad definition often allows individuals who have previously owned a home, but not recently, to qualify for assistance, broadening the pool of eligible participants for long-term accommodation solutions.
The Role of Financial Incentives in Long-Term Accommodation
Financial incentives play a pivotal role in the housing market, particularly for new entrants. For first-time buyers seeking long-term accommodation, these credits directly address some of the most daunting aspects of purchasing a home. A substantial down payment and closing costs can often exceed a buyer’s savings, even if they can comfortably afford monthly mortgage payments. Credits and assistance programs bridge this gap, reducing upfront costs and thereby lowering the barrier to entry for establishing a stable, long-term living arrangement in Arizona.
Key State and Local Programs for Arizona Home Buyers
Arizona offers several robust programs specifically designed to assist first-time home buyers. These initiatives are often administered through the state’s housing department or local entities and are tailored to the unique economic landscape of the region.
ADOH Home Buyer Programs
The Arizona Department of Housing (ADOH) is a central player in providing home buyer assistance throughout the state. ADOH partners with approved lenders to offer various programs that include down payment and closing cost assistance. These programs are typically structured as second mortgages with deferred payments or grants, easing the financial burden on buyers. The exact terms can vary, but the intent is always to provide substantial support for securing a long-term home. Eligibility often involves income limits, credit score requirements, and participation in home buyer education courses.
Down Payment Assistance Options
Down payment assistance (DPA) is arguably one of the most sought-after forms of credit for first-time home buyers. In Arizona, DPA programs can provide funds equivalent to a percentage of the loan amount or a fixed dollar amount to cover the down payment and often a portion of the closing costs.
- Pathway to Purchase (P2P): This program, often available through ADOH, provides significant down payment and closing cost assistance to qualified first-time home buyers in specific counties. It typically comes in the form of a five-year, zero-interest, deferred second mortgage that is forgiven after five years if the buyer remains in the home.
- HOME Plus Loan Program: Another popular ADOH offering, HOME Plus provides a grant for down payment and closing cost assistance. This grant does not need to be repaid, making it an incredibly attractive option for buyers. The grant amount is typically a percentage of the first mortgage loan amount and can be used with various loan types, including FHA, VA, USDA, and conventional loans.
Mortgage Credit Certificates (MCCs)
A Mortgage Credit Certificate (MCC) is a federal tax credit that can provide significant savings for eligible first-time home buyers in Arizona. An MCC allows homeowners to claim a credit for a portion of the mortgage interest paid each year on their federal income tax return. This is not a deduction, but a dollar-for-dollar reduction in their tax liability, which can effectively lower their monthly mortgage payment. The credit typically covers 10% to 50% of the annual mortgage interest, up to a maximum credit of $2,000 per year. This ongoing credit can substantially enhance the affordability of long-term homeownership.
Federal Opportunities for Arizona’s New Homeowners
Beyond state-specific initiatives, federal programs offer foundational support that first-time home buyers in Arizona can leverage. These programs are not exclusive to Arizona but are widely used by residents to secure favorable financing for their long-term accommodation needs.

FHA, VA, and USDA Loans
These government-backed loan programs are instrumental for many first-time home buyers.
- FHA Loans: Insured by the Federal Housing Administration (FHA), these loans require a lower down payment (as little as 3.5%) and have more lenient credit score requirements compared to conventional loans. They are particularly popular among first-time buyers who may not have a substantial down payment saved.
- VA Loans: Offered by the U.S. Department of Veterans Affairs (VA), these loans provide eligible service members, veterans, and surviving spouses with the opportunity to purchase a home with no down payment and no private mortgage insurance. This is an incredible benefit for qualifying individuals seeking long-term accommodation.
- USDA Loans: Backed by the U.S. Department of Agriculture (USDA), these loans are designed for low-to-moderate-income buyers in eligible rural areas. They also typically offer 100% financing, meaning no down payment is required, making homeownership accessible in qualifying parts of Arizona.
First-Time Home Buyer Tax Credits (Historical Context and Current Relevance)
While a large, one-time federal first-time home buyer tax credit like those seen during the 2008-2010 period is not currently active, the principle of tax benefits for homeownership remains. The MCC discussed earlier is a prime example of an ongoing tax credit that directly benefits first-time home buyers by reducing their annual federal income tax burden. Additionally, homeowners can deduct mortgage interest and property taxes from their federal income taxes, which, while not exclusive to first-time buyers, provides substantial long-term financial relief and reinforces the affordability of homeownership.
Navigating the Application Process and Eligibility
Accessing these valuable credits and programs requires understanding and meeting specific eligibility criteria. While requirements vary by program, common factors often include income, credit history, and a commitment to home buyer education.
Income and Purchase Price Limits
Most first-time home buyer assistance programs, especially those providing down payment assistance or MCCs in Arizona, have income limits. These limits are typically set based on the Area Median Income (AMI) for the county where the home is located and vary depending on household size. Similarly, there might be maximum purchase price limits for homes financed through these programs, ensuring that the assistance benefits those buying moderately priced residences for long-term accommodation.
Credit Score and Debt-to-Income Requirements
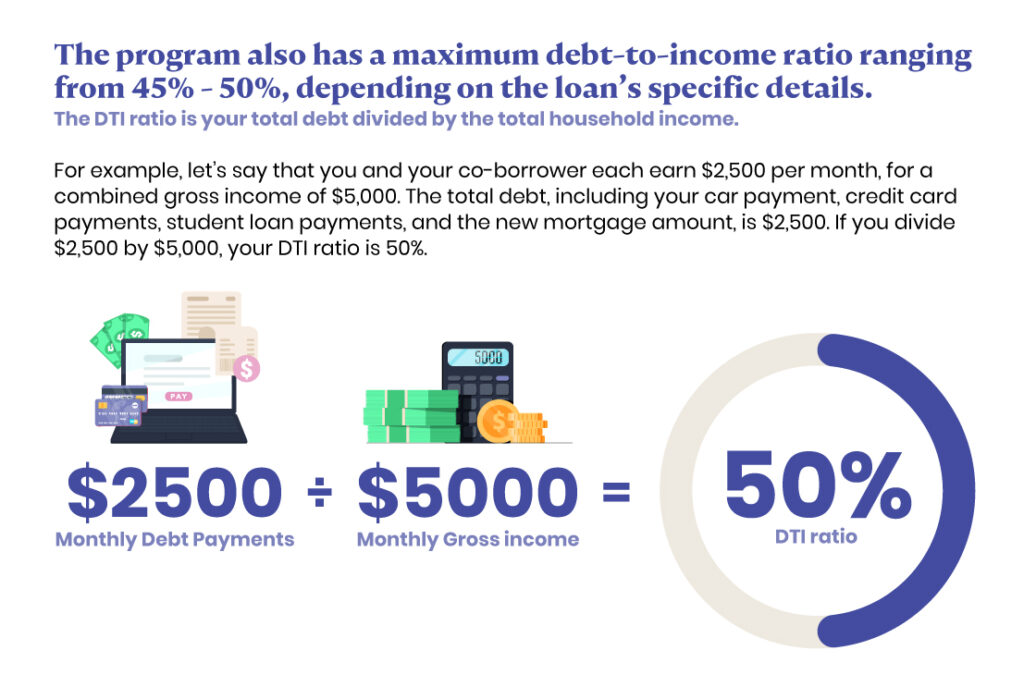
A healthy credit score is generally a prerequisite for mortgage approval, even for government-backed loans. While FHA loans allow for lower scores than conventional loans, most assistance programs will require a minimum credit score. Lenders also scrutinize a buyer’s debt-to-income (DTI) ratio, which compares monthly debt payments to gross monthly income. A manageable DTI demonstrates a buyer’s ability to handle new mortgage payments and is crucial for qualifying for assistance.
Required Home Buyer Education
Many first-time home buyer programs, particularly those from ADOH, mandate participation in a home buyer education course. These courses are designed to equip buyers with the knowledge and tools necessary to successfully navigate the home-buying process, understand the responsibilities of homeownership, and manage their finances effectively for their long-term accommodation. This education empowers buyers to make informed decisions and reduces the risk of foreclosure.
Maximizing Your Credits for a Smooth Transition to Homeownership
For first-time home buyers in Arizona, strategically utilizing available credits can significantly ease the transition into homeownership and ensure the long-term sustainability of their accommodation.
Working with Knowledgeable Lenders and Real Estate Professionals
The complexity of these programs necessitates working with professionals who specialize in first-time home buyer assistance in Arizona. An experienced mortgage lender familiar with ADOH programs, MCCs, and government-backed loans can guide buyers through eligibility requirements, program options, and the application process. Similarly, a real estate agent well-versed in the local Arizona market and these programs can help identify suitable homes that meet program criteria.
Combining Programs for Greater Benefit
One of the most powerful strategies for first-time home buyers is to combine multiple programs. For example, a buyer might utilize an FHA loan for its low down payment requirement, then layer on a HOME Plus grant for down payment assistance, and finally apply for an MCC to benefit from ongoing tax credits. This strategic stacking of benefits can result in substantial savings both upfront and over the life of the loan, making long-term accommodation in Arizona remarkably more affordable. Thorough planning and professional guidance are key to unlocking these combined advantages.
LifeOutOfTheBox is a participant in the Amazon Services LLC Associates Program, an affiliate advertising program designed to provide a means for sites to earn advertising fees by advertising and linking to Amazon.com. Amazon, the Amazon logo, AmazonSupply, and the AmazonSupply logo are trademarks of Amazon.com, Inc. or its affiliates. As an Amazon Associate we earn affiliate commissions from qualifying purchases.